
Reverse mortgages · Orange County, CA
Stay in the home you love. Let the equity you’ve built support the retirement you planned.
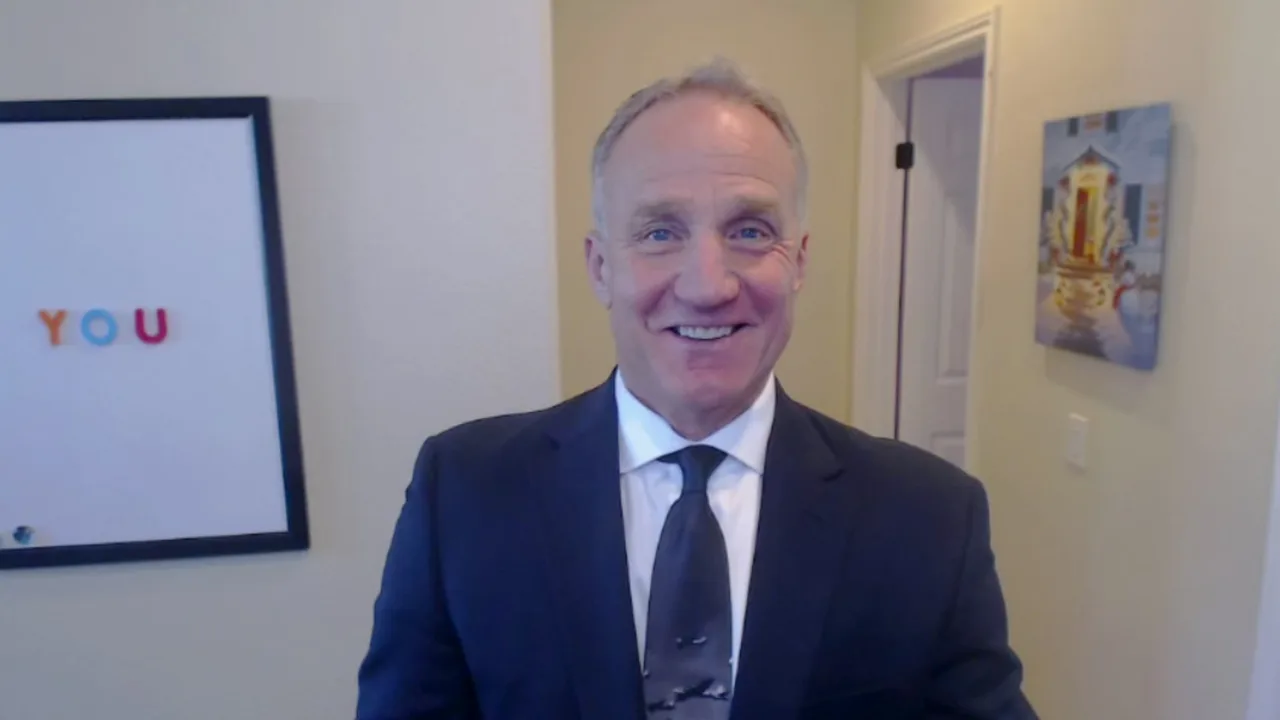
Paul Scheper has spent 40 years in mortgage lending — the last 20 focused on reverse mortgages. He’ll tell you plainly whether one belongs in your plan. If it doesn’t, he’ll say so.
- No credit pull
- Not a loan application
- Paul follows up personally
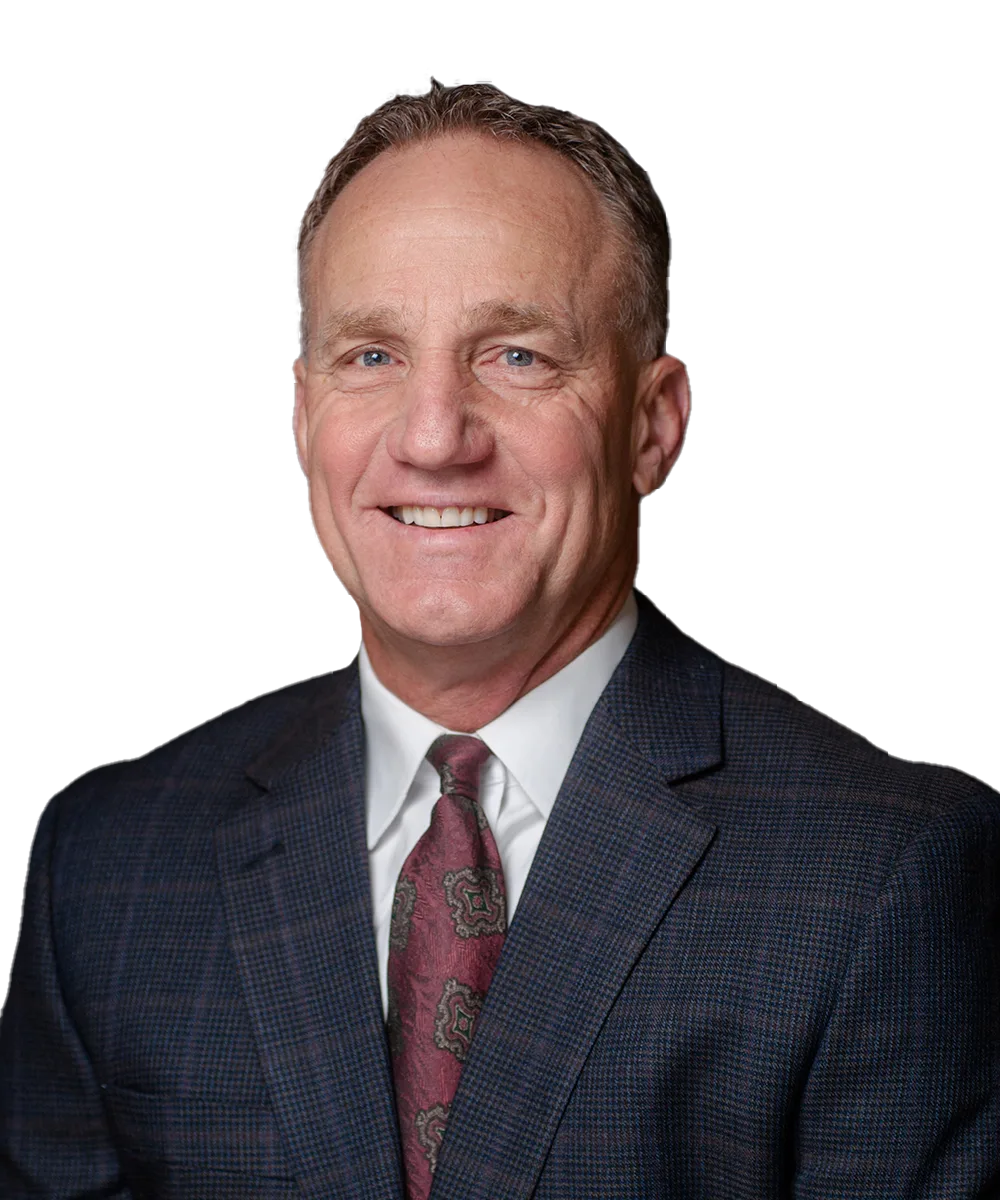
- Founder, Reverse Mortgage Training Institute
- National Field Sales Manager, Liberty Reverse Mortgage
- Certified Senior Advisor (CSA)
- Orange County “Man of Character,” 2004
- Author, The Psychology of Improving
- Harvard University · USC Marshall
- California Real Estate Broker since 1984
- Published in The Reverse Review
The idea
Home equity as a retirement tool — not a last resort.
A reverse mortgage can convert part of the equity you’ve built into cash you can use on your terms — monthly advances, a line of credit, or a lump sum — without a required monthly mortgage payment in most cases. You remain the owner. Property taxes, insurance, and upkeep stay your responsibility.
Paul frames it around what he calls the three C’s of retirement: choice, control, and comfort. If a reverse helps you keep all three, it’s worth a conversation. If it doesn’t, he’ll say so.
Traditional mortgage
You pay the lender every month. Equity builds, but it stays locked in the walls.
Reverse mortgage
Part of that equity comes back to you. No required monthly mortgage payment while you live there and meet the terms.
Why Paul
The person other reverse specialists learned from.
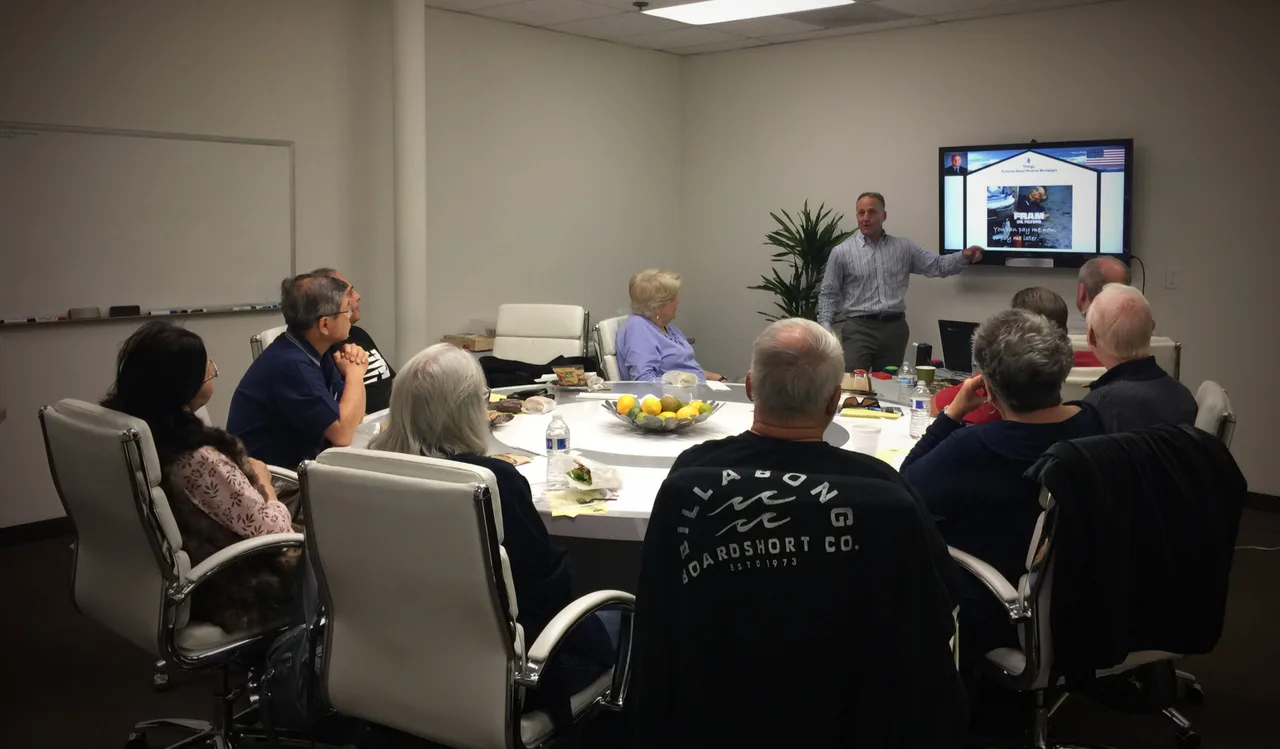
Most loan officers add reverse mortgages to a menu. Paul built his career on them — founding a reverse training institute, leading national reverse sales teams, and writing the industry’s “ABCs of Originating Reverse Mortgages.” A Harvard psychology degree and a USC finance MBA mean he explains the human side and the numbers side in the same breath.
- 0Years in mortgage lending
- 0Years focused on reverse
- 0Senior-lending designations
- 0Desk — your file never leaves it
- Designations
- CRMP (Certified Reverse Mortgage Professional) · CSA (Certified Senior Advisor) · CA Real Estate Broker since 1984
- Industry roles
- Founder, Reverse Mortgage Training Institute · National Field Sales Manager, Liberty Reverse Mortgage · Built a HECM retail division from the ground up
- Education
- Harvard University, BA Psychology · University of Southern California, MBA Finance
- Published
- “The Golden Rule of HECM Origination” and “The ABCs of Reverse Mortgage Originating,” The Reverse Review · Author of The Psychology of Improving
Father & daughter team
A family business, for your family’s biggest decision.
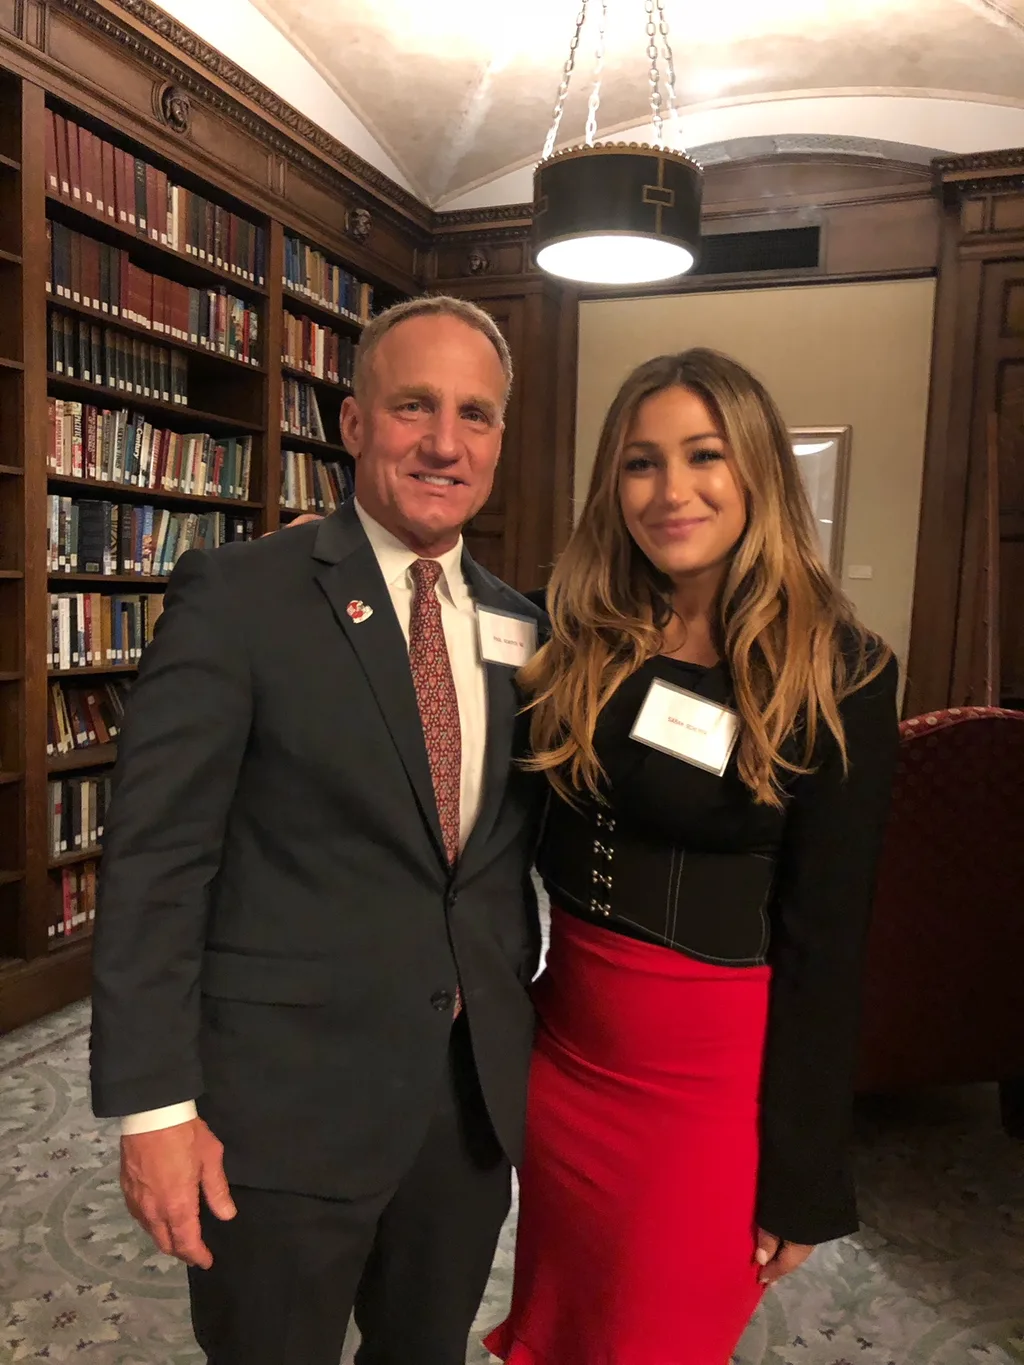
Paul works alongside his daughter, Sarah Scheper, Vice President of Loangevity Mortgage. When you call, you get two people who answer their own phones, know your file, and understand that a reverse mortgage is a conversation about a home — usually with adult children in the room.
“Reverse mortgages are about more than dollars — they’re about peace of mind. They give seniors options, security, and the ability to live with dignity in the home they love.”
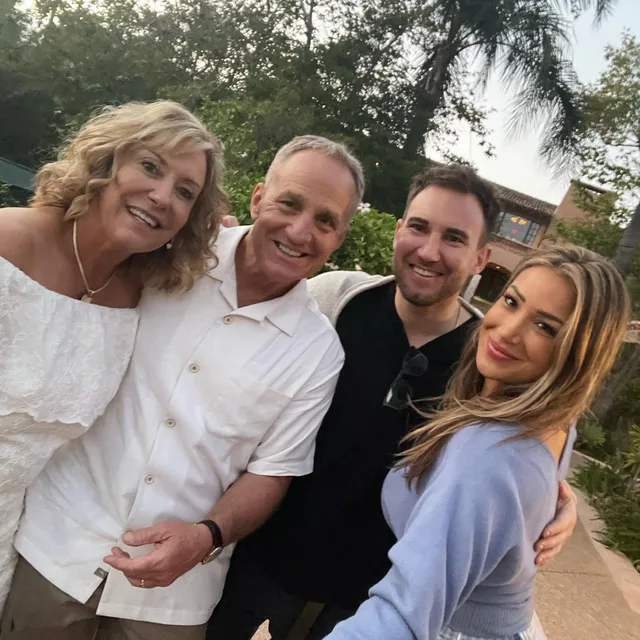
- Married 41 years to his high-school sweetheart, Gigi
- Father to Scotty and Sarah · Indianapolis-born, Orange County for life
- Two pugs, Winston and Pepper, who attend most Zoom calls
Soft fit check
Is this worth exploring?
These loans are designed for older homeowners with a primary residence and enough equity to make the conversation useful. Exact age and property rules can vary by program — Paul confirms what applies to you.
-
Older homeowner
Many programs start around age 62; others differ. Don’t assume you’re out — ask.
-
Primary residence
Built for the home you live in, not a vacation or investment property.
-
Meaningful equity
You don’t always need the home paid off. An existing mortgage is often addressed at closing when equity is there.
What clients say
Kind words from the kitchen table.
Reviews shared publicly by clients on PaulScheper.com.
Next
What happens when you reach out
Share a few details about your home and goals. Paul reviews the scenario and follows up personally. No hard credit pull from this step. No obligation to proceed.
-
A few details
Your home, your goals, and how to reach you. Not a loan application. No credit pull.
-
Paul reviews it personally
Paul reads the scenario and follows up himself — phone details are on the confirmation page.
-
You decide
If a reverse belongs in the plan, counseling and disclosures come next. If it doesn’t, you’ll hear that too.
Ready when you are
The New American Dream is staying in the home you already love.
Paul’s mission is simple: help homeowners overcome the fear of outliving their money. Share a few details and he takes it from there — no pressure from a webpage.