
For homeowners who've built up serious equity over the years
Your Home Is Sitting on
Thousands of Dollars.
Access It With No Monthly Payments.
Homeowners 62+ can turn built-up equity into cash with no required monthly mortgage payment. The quiz takes 60 seconds.
- No credit pull
- Takes 60 seconds
- Free, no obligation
- Equity you own
- $250,000+
- Mortgage left
- Paid off first, out of the same equity
Example home. Your numbers will differ.
- 5.0 18 client reviews on Experience.com
- 11 States licensed, NY to FL to CA
- #305398 Individual NMLS, verifiable at NMLS Consumer Access
-
 Company NMLS #2072896
What the program does
Your equity, working for you. Your name stays on the deed.
For homeowners 62 and older, one federally insured program can do any of these. Russ helps you pick the shape that fits your plan.
-
Stop making a monthly mortgage payment
Pay off your current mortgage at closing and keep the home. Property taxes, insurance, and upkeep still stay with you.
-
Monthly income you can count on
Steady monthly advances from your equity to cover the gap between Social Security and real life.
-
A line of credit that grows
Leave it untouched and the available amount grows over time. Draw only when you need it.
-
Pay for care and stay home
Fund help at home instead of a rushed move. The house stays in your name.
-
Buy your next home, no monthly payment
Right-size or move closer to family using the purchase version of the same program.
The loan balance grows over time and is repaid when the last borrower leaves the home. What is left after repayment belongs to you or your heirs.
Same house. Very different month.
-
Today
- A mortgage payment due every month
- Equity locked in the walls
- One surprise expense away from selling
- Your kids quietly worrying about the house
-
With the program
- No required monthly mortgage payment while you live there and meet the loan terms
- Equity available as cash, monthly income, or a line of credit
- Title stays in your name. You own the home, the lender holds a lien
- Federally insured, non-recourse: you and your heirs never owe more than the home is worth
You remain responsible for property taxes, homeowners insurance, HOA dues, and maintenance. Interest and fees are added to the balance over time, which can reduce the equity left for heirs. Russ walks through every number before you decide anything.
How it works
Sixty seconds now. A real conversation after.
-
Take the 60-second quiz
A few questions about your home, your age, and what you want the money to do. No credit pull. No obligation.
-
Russ reviews it and calls you
Not a call center. Russ reads what you shared, then reaches out personally to walk through what the program could look like for you.
-
You decide, at your pace
If it fits, independent counseling and full disclosures come before any application. If it does not fit, Russ tells you that too.
Sound like you? Then it is worth sixty seconds.
These are the basics. The quiz sorts out the rest, and Russ confirms the details on the call.
- 62 or older (one spouse is enough)
- Own your home or have significant equity
- It is your primary residence
- House, condo, or 2 to 4 unit property
- NY
- NJ
- CT
- PA
- MD
- FL
- GA
- ME
- CO
- NV
- CA
What clients say after the closing.
5.0 18 reviews on Experience.com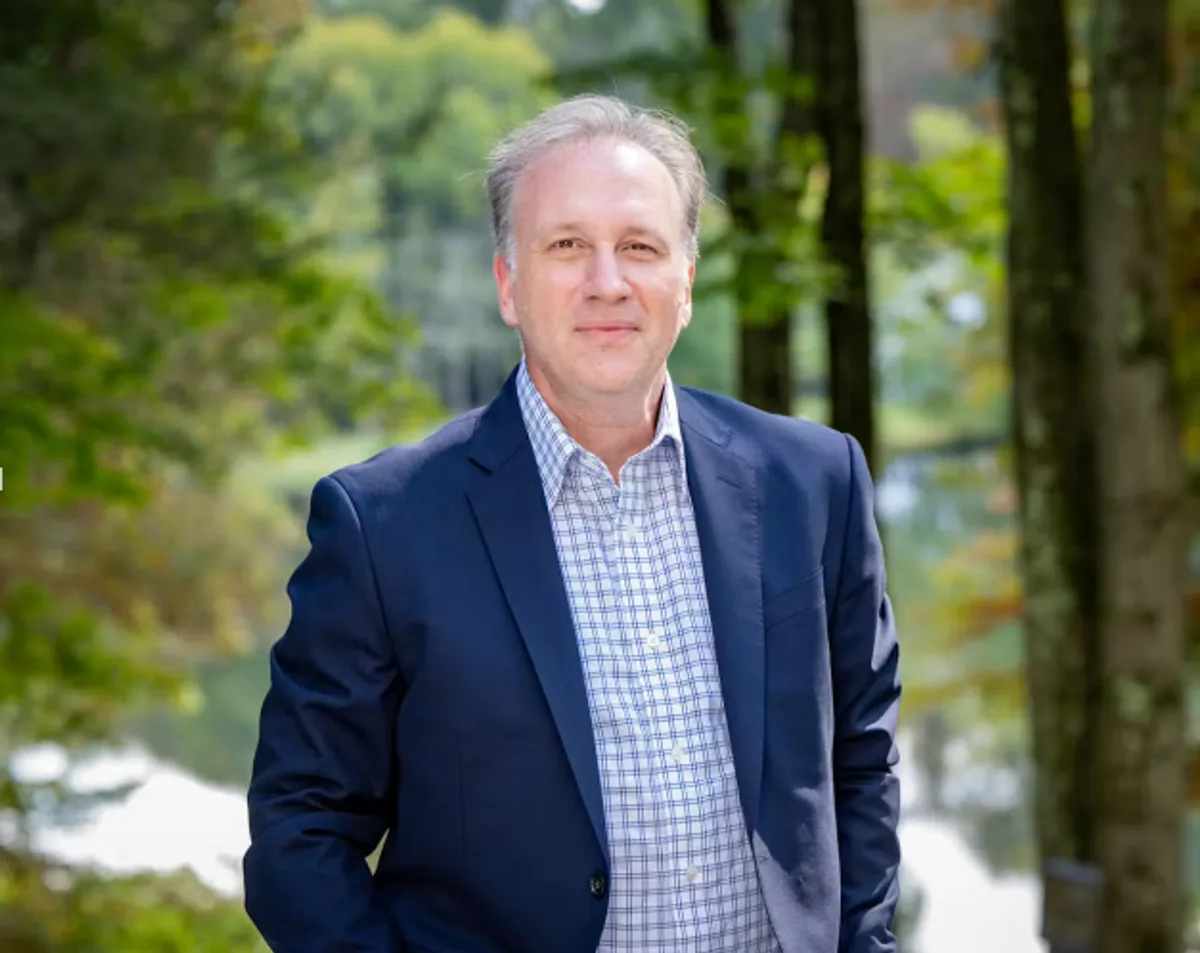
Meet Russ, the person who actually calls you back.
Russ is a Long Island native, a Retirement Mortgage Expert at Go Rascal Inc. (NMLS #305398), and the person who actually picks up when you call. He explains the tradeoffs plainly, in your kitchen or over the phone, and tells you when a program is not the right fit.
- Licensed in 11 states under NMLS #305398
- Long Island native and proud dog dad
- Explains the tradeoffs in plain English, and says so when it is not a fit
Powered by Go Rascal Inc., a licensed mortgage company (Company NMLS #2072896). Loans are arranged with third-party lenders, so the program is matched to you rather than one bank's menu.
Find out what your home could do for you.
Sixty seconds. No credit pull. Russ follows up personally.